
Fix & Flip Strategy · 2026
The old fix-and-flip playbook is broken. Smart investors are rewriting the rules and winning big by doing less.
Skip Schenker · Founder, ReadyForRemodel.com April 2026
Let me tell you what a lot of fix-and-flip investors don't want to admit out loud: the last eighteen months have been brutal.
Not rough. Not challenging. Brutal.
The data doesn't lie. According to ATTOM's 2025 year-end report, gross profit per flip dropped from $77,000 in 2024 to $65,981 last year. ROI fell to 25.5% the lowest return since 2007. Profit margins declined for six consecutive quarters. And that average investor held their property for 165 days, nearly five and a half months before selling. That's five and a half months of hard-money interest, property taxes, insurance, and carrying costs eating away at whatever was left of the margin.
25.5%
Average flip ROI in 2025 — lowest since 2007
165
Avg. days from purchase to sale in 2025
$80K
Avg. renovation budget — 16% of sales price
8.3%
Avg. discount investors took on final sales price
As Scotsman Guide reported, average renovation expenses hit $80,000, representing 16% of average sales prices, while financing costs averaged 9.8%, making borrowing harder and more expensive than it has been in a generation. The RCN Capital team put it plainly: profit margins were hitting possibly the lowest levels they had seen in a "significant" amount of time.
So what happened? A perfect storm, and investors who understood each piece of it are the ones still standing.
The Three-Headed Monster
First came the labor shortage. The Associated General Contractors of America reported that 92% of construction firms struggle to find qualified workers. The industry needed nearly 454,000 additional workers in 2025 just to keep pace with existing demand and that number could reach 520,000 by late 2026. The result: NAHB's own research showed labor shortages added an average of nearly two additional months to every residential project. Wages for skilled tradespeople climbed 4.5% to 9% year over year. Licensed plumbers now command $85 to $175 per hour, up 8 to 10% from 2025. Electricians are running $60 to $145 per hour, up another 6 to 8%.
Then came the materials. Tariff volatility, supply chain disruptions, and inflationary pressure pushed renovation costs higher every quarter. Investors who budgeted in January were fighting a different cost structure by March.
"In a high-rate environment, buyers are effectively financing the value of improvements at a higher interest rate - making pre-renovation fixer-uppers comparatively more attractive for buyers willing to put in sweat equity." Joel Berner, Senior Economist, Realtor.com
And then the buyer pool softened. Realtor.com data shows that flipped homes, which once garnered 25% more page views per listing than comparable unrenovated homes in 2021, saw that advantage shrink to just 6.5% by late 2025. High mortgage rates made buyers reluctant to finance the full cost of a renovated property, forcing investors to slash prices an average discount of 8.3% on final sales prices. The premium for a fully remodeled home quietly disappeared.
Where Investors Are Bleeding the Most
Here's what doesn't get talked about enough: the most expensive, most time-consuming, and most variable part of any flip is not the roof. It's not the HVAC or the electrical panel. It's the finishes.
A kitchen remodel alone ranges from $18,000 for a minor refresh to $55,000 or more for a full gut and those numbers are up 19 to 22% since 2022, according to Houzz's Kitchen Trends Study. A bathroom remodel runs $16,500 on average, with a full gut running $30,000 to $60,000. Cabinets alone can run $2,000 to $28,000 depending on what you choose. Appliance packages, countertops, flooring, lighting, tile; every one of those line items carries an enormous range from builder-grade to luxury, and getting those decisions right is genuinely hard.
The 2024 Houzz & Home Study found that 39% of homeowners who renovated exceeded their budget and 24% never set one at all. Investors trying to guess what the buyer will want and value face the same problem. Overspend on finishes and you eat the premium. Cut corners and buyers can smell it on day one of showings.
The finish phase is where projects stall. It's where contractor availability is worst; tile setters, cabinet installers, countertop fabricators. It's where decision fatigue sets in. And it's where most of those 165 days on the clock are disappearing.
The Strategy That's Winning Right Now
The smartest investors I know have completely changed the playbook. They're not trying to do less, they're doing the right things.
The old model
Full renovation, full risk
The winning model
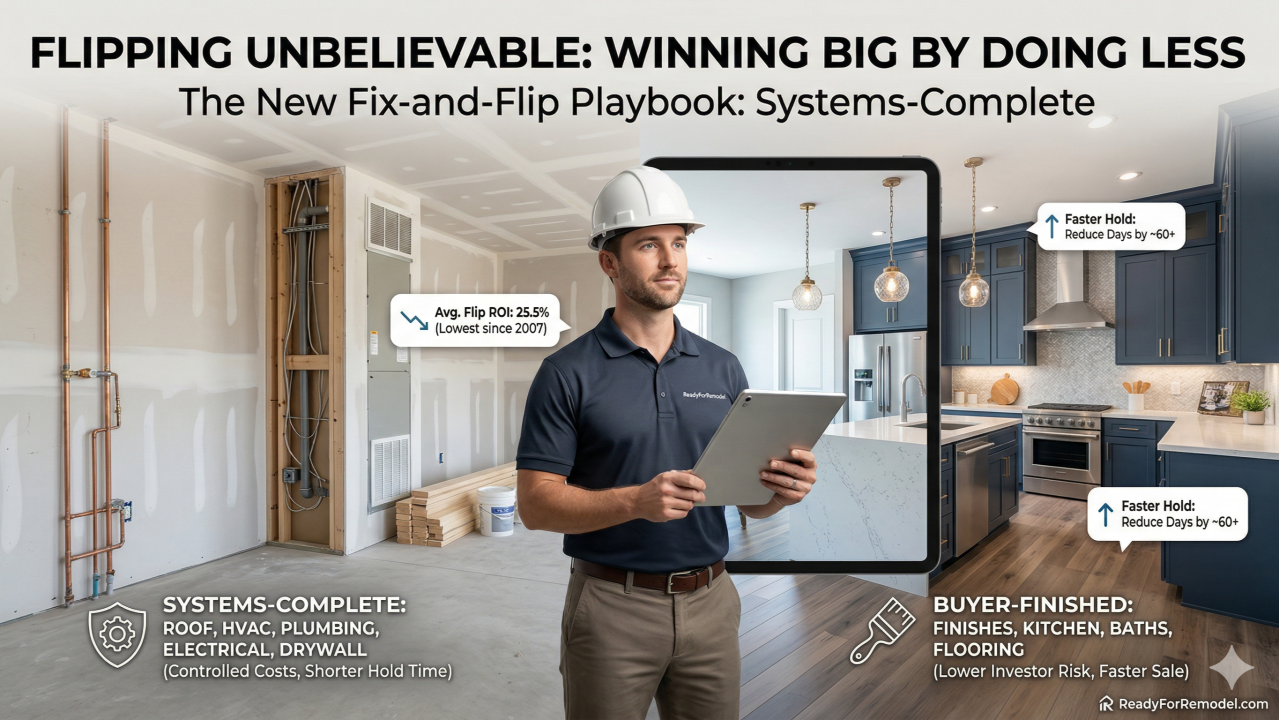
Systems-complete, buyer-finished
Here's the logic, and it's airtight.
A new roof lasts 25 to 30 years. A new HVAC system delivers comfort and efficiency for 15 to 20 years. New plumbing and electrical are invisible but invaluable and they're what appraisers, inspectors, and lenders care most deeply about. These are the systems that protect the buyer for decades. They're also the systems where an investor can control costs with precision, because material and labor costs for mechanicals are far more predictable than the chaos of finish selections.
The buyer, meanwhile, gets something the old model never offered: a home that's theirs before the paint dries. They choose the countertops. They pick the cabinets. They select the flooring, the appliances, the light fixtures at the quality level they can afford and in the style that reflects who they are. And they finance all of it through a single renovation loan at owner-occupied rates; FHA 203(k), Fannie Mae HomeStyle, or Freddie Mac's CHOICERenovation with as little as 3 to 5% down.
This is where technology changes everything. Tools like the AI Visualizer on Ready4Remodel.com let buyers see exactly what their finished home will look like before a single cabinet is ordered. They can try different countertop materials, swap flooring styles, change paint colors, and explore appliance packages — all tied to real product pricing so their renovation budget is grounded in reality, not imagination. A buyer who can see their dream home clearly is a buyer who is ready to write an offer today.
Why This Is a Win for the Investor
Think through what changes when you stop at drywall and sell a systems-complete home.
You eliminate the finish phase entirely the most unpredictable, most delayed, most decision-intensive part of the project. You dramatically shorten your hold period, which directly reduces every line of carrying cost. You stop gambling on whether the gray LVP flooring you chose is what this particular buyer wanted. And you present to a market that is genuinely hungry for this type of opportunity; buyers who've been priced out of move-in-ready homes but have excellent credit and stable income, who just need a canvas and the right financing to get there.
Realtor.com's own senior economist noted it clearly: in a high-rate environment, buyers are increasingly attracted to pre-renovation properties where they can finance the improvements at the lower rate embedded in a renovation loan. You're not selling a half-finished house. You're selling a promise backed by solid bones, a solid loan product, and a technology platform that makes the vision tangible on day one.
"The most expensive part of a flip isn't the roof or the HVAC. It's the finishes and the carrying costs that accumulate every day you're still choosing them."
Fewer decisions. Shorter hold. Controlled costs. Faster close. That's the formula.
The Numbers That Tell the Story
Consider what's at stake. If the average investor saved even 45 to 60 days off a hold period by eliminating the finish phase, just two months off that 165-day average the carrying cost savings alone at a 9.8% annualized hard-money rate on a $250,000 loan represent roughly $3,500 to $4,000 back in your pocket, before you count the labor and material costs you never spent.
Now multiply that by the fact that 39% of renovators exceed their budget on finishes, and the average kitchen overage on a flip can easily run $10,000 to $20,000 when scope creep, delays, and re-orders set in. The math starts to look very different from the 25.5% ROI the industry is reporting across the board.
This Is the Pivot That Matters
The fix-and-flip industry is not dying. It's evolving. The investors who are winning in 2026 are the ones who recognized that trying to do everything for the buyer, guessing their taste, overspending on cosmetics, absorbing the delays of a labor market that can't find enough tile setters is a losing strategy in this environment.
The investors who are building wealth right now are the disciplined ones. They're doing the hard, unglamorous work that nobody sees: the new roof, the new mechanicals, the clean electrical panel, the plumbing that will never leak. They're handing the buyer a blank slate and the tools to make it theirs. And they're getting to the closing table weeks faster with a healthier margin than anyone who went the traditional route.
This is "Fix & Live" financing meeting fix-and-flip strategy. It's a collision of two worlds that creates value for everyone in the transaction, the investor who gets out faster and cleaner, the first-time buyer who gets the customization and equity that the old model reserved for people who could afford a fully renovated home, and the broader housing market that desperately needs more of this inventory in more cities.
That's not just a good investment strategy.
That's flipping unbelievable.
Want to see this strategy in action?
Explore the AI Visualizer and renovation loan tools at ReadyForRemodel.com and share this article with every investor and Realtor in your network who's been wondering why the old playbook stopped working.
Sources: ATTOM 2025 Year-End U.S. Home Flipping Report · Scotsman Guide / March 2026 · John Burns Real Estate Consulting Q1 2025 Fix-and-Flip Survey · Associated General Contractors of America 2025 Workforce Report · NAHB Labor Shortage Study (June 2025) · Realtor.com Flip Factor Analysis (Dec 2025) · Houzz 2024 Kitchen Trends Study · Bridgit 2025 State of Workforce Planning